Free shipping · 0% for 6 months · White-glove available

Buy Now, Pay Later Dining Sets: How to Finance Your Table

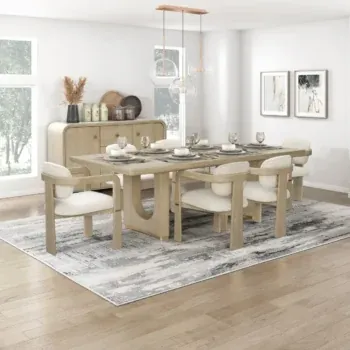
Reviewed by the Mobilia Cleopatra design team
Quick answer: Yes, you can buy a dining set now and pay later. At Mobilia Cleopatra you choose a dining table, chairs or a complete set, then pick a payment partner at checkout: Synchrony, Affirm, or the lease-to-own providers Koalafi, Acima and Snap Finance. Plans typically run for 3, 6 or 12 months, and the provider sets the final terms, approval and any fees. Measure the room first, then compare the total cost of each plan before you accept one.
A dining set is one of the larger purchases most households make for the home. It is a table, four to eight chairs, sometimes a bench or a buffet, and it will be used every day for years. That is exactly why so many shoppers look for a buy now, pay later dining set: spreading the cost over a few months can make the right set possible now instead of a stopgap table that gets replaced later.
A payment plan, though, only changes how you pay. It does not change whether the table fits the room, whether the chairs pull out without hitting the wall, or what the frame is made of. This guide answers the payment question directly, then walks through what to measure, what to compare and how to read an offer, so the set you finance is one you will still be glad you chose when the last payment clears.
Mobilia Cleopatra is a U.S. furniture house based in Upland, California, offering traditional, French-style, Victorian and contemporary dining furniture, plus the handmade Kleopatra Kingdom® collection. Offers change, so always read the terms on the screen in front of you. This page is general guidance, not a loan agreement.
Can You Buy a Dining Set Now and Pay Later?
Yes. Buy now, pay later (often shortened to BNPL) lets you take your dining set home and split the price into a series of smaller payments instead of paying the full amount at checkout. The Consumer Financial Protection Bureau describes BNPL as a type of installment loan that typically lets you buy something immediately with little or no initial payment. For furniture, the term is used more broadly: it can mean a short pay-in-four plan, a longer monthly installment loan, a promotional financing account, or a lease-to-own agreement.
The process for a dining set is simple:
- Choose your table, chairs or complete set from the dining sets collection.
- Add the pieces to your cart and select a payment partner at checkout.
- Complete the provider’s short online application. The provider, not the store, decides approval and terms.
- Review the payment schedule, the number of payments, any interest or fees, and the total you will pay. Accept only if it fits your budget.
Because the agreement is with the financing provider, two shoppers can see different offers for the same dining set. Eligibility, the purchase amount and the plan length all shape what appears. For a full overview of every partner and how each one works, see our payment options page.
The Best Way to Pay for a Dining Table Set You Can’t Pay for All at Once
There is no single best way for everyone. The right answer depends on how soon you need the table, how predictable your income is, and how much the total cost matters to you compared with the monthly amount. Here is how the common options compare for a dining set.
| Option | How it works | Cost to watch | Best suited to |
|---|---|---|---|
| Save and pay in full | You set money aside and buy when you have the full amount. | No financing cost; the trade-off is waiting. | Shoppers who can wait and want the lowest total. |
| Promotional financing (such as Synchrony) | A financing account with promotional plans for eligible buyers. | Read what happens if the balance is not paid by the end of the promotion. | Buyers with steady income who can clear the balance on schedule. |
| Installment plan (such as Affirm) | A fixed schedule of payments shown before you confirm. | APR depends on credit and plan length; check the total. | Buyers who want a set number of fixed payments. |
| Lease-to-own (Koalafi, Acima, Snap Finance) | You lease the furniture and own it only by meeting the terms of the lease agreement. | Usually costs more than the retail price in total. | Shoppers with limited or no credit history. |
A practical rule: if you can pay the set off within a 0% promotional window, that is usually the least expensive way to spread the cost. If you need longer, compare the total on each offer rather than the monthly figure alone. A lower monthly payment over a longer term can cost more overall.
It also helps to know that short and long plans are different products. As of October 2026, Affirm states that its Pay in 4 plans are 0% APR, while its longer monthly plans range from 0% to 36% APR based on credit and are subject to an eligibility check; which plans you see depends on the purchase amount. Because a full dining set is a sizable order, a longer plan is often what appears. Our comparison of Affirm and Klarna for furniture explains the difference between pay-in-four and monthly plans in more depth.
Payment Options for Dining Sets at Mobilia Cleopatra
Mobilia Cleopatra works with five financing partners, and every one of them can be used on dining furniture, from a four-seat kitchen table to a formal set for eight or more. Our payment page lists them as follows:
- Synchrony: a financing account for furniture purchases, with promotional plans such as up to 0% interest for up to 6 months for eligible buyers.
- Affirm: pay-over-time plans with a clear payment schedule shown before you confirm.
- Koalafi, Acima and Snap Finance: lease-to-own options that may suit shoppers with limited or no credit history.
Plans typically run for 3, 6 or 12 months. The exact length, approval and any fees are set by the provider and depend on your purchase and eligibility. We do not offer Klarna, Afterpay or Sezzle at checkout, so if you are comparing plans you have seen elsewhere, compare them against the five partners above.
Lease-to-own deserves a closer look before you choose it for a dining set. It can open the door when credit history is thin, but it is a lease rather than a loan, and the total you pay usually ends up above the retail price. If that is the route you are considering, our guide to furniture with no credit check explains how these agreements work and what to read before you sign.
If you are unsure which partner fits your order, call our team at (909) 999-1442. We can help you confirm the pieces and sizes in your cart before you apply, so the amount you finance matches the set you actually want. You can also see dining pieces in person at our Upland showroom at 280 N Benson Ave, Suite 6, Upland, CA 91786.
Kitchen Table Payment Plans: Smaller Sets, Counter-Height Tables and Chairs
A payment plan is not only for a formal dining room. Many shoppers searching for a kitchen table payment plan want a compact set for a breakfast nook, a counter-height table for an open kitchen, or replacement chairs for a table they already own. The same five partners apply, and a smaller order often means a shorter plan or a lower total to manage.
Counter-height and pub-style sets
Counter-height tables sit higher than a standard dining table and pair with taller chairs or stools. They suit kitchens where the table doubles as a prep or homework surface, or where you want the seating to line up with an island. Browse counter-height tables and check that the seat height of the chairs matches the table you choose. A mismatch here is uncomfortable every single day, and no payment schedule fixes it.
Financing chairs or a bench on their own
If your table is in good shape, replacing only the seating can transform the room for a fraction of the cost of a full set. You can finance dining chairs and benches as their own order, as long as a plan is offered on that purchase amount. Before you order, measure your existing table’s height and the space between its legs or under its apron, so the new chairs tuck in properly.
Smaller orders are also a good place to think about the total rather than the monthly payment. Adding a few extra months to a modest purchase can raise the overall cost without making much difference to your monthly budget.
Measure Before You Finance
The most common regret with a financed dining set is not the payment plan. It is a table that is too long for the room or chairs that hit the wall. Measuring first protects both your room and your budget, because you will be paying for the set for months.
- Seating width: plan on roughly 24 inches of table edge per diner so elbows are not crowded.
- Clearance behind chairs: allow about 36 inches between the table edge and a wall or furniture so a chair can pull out and someone can pass behind it. Main walkways need more.
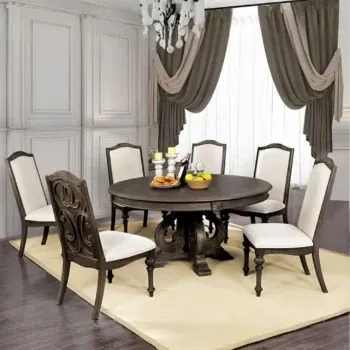
- Legs and bases: a curved cabriole leg or a carved pedestal base reaches farther than a straight leg. Measure to the outermost curve, not the tabletop.
- Rug size: if the set sits on a rug, the chairs should stay on the rug when pulled out.
- Delivery path: measure doorways, hallways and stair turns, especially for a large one-piece tabletop.
Write down the table length, width and height, the chair height and the overall footprint before you compare offers. Then browse dining tables with those numbers in hand. If no standard length fits your room, ask our team about a custom order before you apply for financing, so the plan covers the piece you really need.
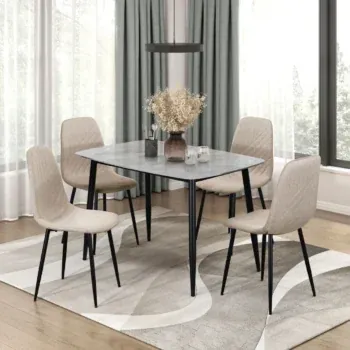
What a Payment Plan Does Not Change
A monthly plan makes a dining set easier to fit into a budget, but it does not change the furniture itself. Judge the set exactly as you would if you were paying in full.
Materials. The product description should name the wood or the material: oak, walnut, cherry, mahogany or beech for wood pieces, or the stone, glass or veneer used for the top. Chair upholstery should name its fabric or leather. If a listing is vague, ask before you finance.
Construction. Look at how the legs attach, whether the chairs have corner blocks or stretchers, and what finish protects the top. These details decide how the set holds up to daily meals far more than the price tag does.
Style and scale. A carved French-style set with curved legs and a high-backed Victorian set occupy space differently from a simple rectangular table. If you love an ornate look, read our guide to French-style dining sets to see how scale and detail work together before you attach a plan to a photo.
Handmade pieces. The Kleopatra Kingdom® line is genuinely handmade, and those sets are built with carving and finishing that take time. If you are considering one, our page on handmade dining sets explains what to expect. The rest of the catalog is curated name-brand furniture, and you should compare it on its own stated materials.
A 0% offer is a reason to read the term, not a reason to buy a larger set than the room can hold.
How to Read a Dining Set Financing Offer Before You Accept
Every offer screen shows the key numbers. Take a minute with each one before you click accept.
- Total cost: the full amount you will pay by the end, including any interest or lease fees. Compare it with the cart price.
- Number and timing of payments: how many payments, how often, and when the first one is due.
- Interest or promotional terms: whether the plan is interest-free, carries an APR, or has a promotional period, and what happens after a promotion ends.
- Down payment: some plans ask for an amount up front, which changes what you need on delivery day.
- Late payments: the CFPB notes that while many BNPL loans charge no interest, most charge late fees for missed payments. Automatic payments from an account without enough funds can also trigger bank overdraft or NSF fees.
- Returns: your repayment agreement is with the provider, not the store. The CFPB warns that returning something bought with BNPL can be complicated, so read both the store’s return terms and the provider’s terms.
The CFPB’s simplest advice applies well to furniture: make sure the payments fit your budget, and remember that qualifying for a plan does not mean you have to use it. If you are new to these plans, start with our explainer on how buy now, pay later furniture works, then come back to compare dining sets.
Once the numbers check out, finish the order with the same care you used to choose the set: confirm the finish, the number of chairs, and the delivery address and access.
Frequently Asked Questions
Can you buy a dining set with buy now, pay later?
Yes. At Mobilia Cleopatra you can use Synchrony, Affirm, Koalafi, Acima or Snap Finance on dining sets, tables, chairs and benches. Plans typically run for 3, 6 or 12 months, and the provider sets the final terms and approval. You choose the plan at checkout after adding the pieces to your cart.
What is the best way to pay for a dining table set when I can’t afford it all upfront?
If you can pay the set off within a 0% promotional period, that is usually the least expensive way to spread the cost. If you need longer, compare the total cost of each installment offer, not just the monthly payment. Lease-to-own can help with limited credit, but it usually costs more than the retail price in total.
Is there a payment plan for a kitchen table?
Yes. The same payment partners apply to kitchen tables, compact dining sets and counter-height tables. A smaller order may qualify for a shorter plan, which can keep the total cost down. Check that a plan is offered on your purchase amount when you reach checkout.
Does buy now, pay later affect my credit?
It depends on the provider and the plan. According to the CFPB, most BNPL loans do not involve a hard credit inquiry, but your creditworthiness may be evaluated with each purchase. The FTC notes that some providers may report payment history to the credit bureaus, and late or missed payments could hurt your score.
Can I finance only the dining chairs?
Yes, chairs or a bench can be their own order, provided a plan is offered on that amount. Measure your current table’s height and the space under it first, so the new seating tucks in and matches the table comfortably.
What happens if I return a financed dining set?
Your repayment agreement is with the financing provider, not the store, so returns can take extra steps. The CFPB advises checking the return policy before you buy. Read both the store’s return terms and your provider’s terms before you accept the plan.
Should I choose a bigger dining set because the plan is 0%?
No. A 0% offer only applies for the term printed on it, and a larger set still has to fit your room and walkways. Pick the set that fits first, then choose the plan that fits your budget.
Final Thoughts
Buying a dining set now and paying later can be a sensible way to get the table your household will use every day, as long as the order is right before the plan is. Measure the room, the clearance behind each chair and the delivery path. Confirm the materials and construction. Then compare the offers from Synchrony, Affirm, Koalafi, Acima and Snap Finance by their total cost, not only by the monthly figure.
Whether you are financing a compact kitchen set, a counter-height table, a set of replacement chairs or a formal dining room for eight, the same order of decisions applies: fit first, quality second, payment third. When you are ready, our team is happy to help you check sizes and pieces before you apply. Call (909) 999-1442 with questions about a specific set or a plan.
This article is general information, not financial advice. Terms, approval and fees are set by each provider and can change; specific provider terms are stated as of October 2026.