Free shipping · 0% for 6 months · White-glove available

Affirm vs Klarna for Furniture (and Afterpay)

Reviewed by the Mobilia Cleopatra design team
Quick answer: Affirm vs Klarna for furniture comes down to the plan type and the total you will pay, not the brand name. Both offer an interest-free pay-in-4 option and longer monthly financing that may carry interest depending on eligibility. For a large furniture order, compare the full cost over the whole term. At Mobilia Cleopatra, Affirm is one of five financing partners; Klarna and Afterpay are not among the partners listed on our buy now, pay later furniture page.
Affirm and Klarna are payment plans, not furniture grades. The better plan is the one whose total, term, and late-payment rules you have actually read, and neither one fixes a sofa that does not fit the room. This guide is written for U.S. shoppers weighing a furniture order, from a single accent piece to a complete living room set. It explains how each provider structures its plans, where Afterpay fits into the comparison, what to check before you finance a sofa set, and which payment options are actually available when you shop with us in Upland, California.
One note before we begin: payment terms change, and they are set by the provider, not by the store. Where we describe a specific term below, it reflects what the provider’s own pages stated as of October 2026. Always read the offer on your screen at checkout and the provider’s current terms before you confirm anything. This page is not a loan agreement.
Affirm vs Klarna for Furniture: How They Compare
On the surface, Affirm and Klarna look similar. Both let you split a purchase into smaller payments, both advertise an interest-free pay-in-4 plan, and both offer longer-term monthly financing for bigger purchases. The differences show up in the details: how the longer plans are priced, who issues the loan, how eligibility is checked, and how each provider handles a missed payment.
For furniture, those details matter more than they would for a pair of shoes. A sofa set, a dining table, or a bedroom suite is usually a larger order, which means two things. First, a pay-in-4 schedule compresses a big number into a few weeks, so each installment may be larger than your budget allows. Second, a longer monthly plan spreads the cost out but may add interest, and a smaller monthly figure can still mean a higher total. That is why the honest answer to “Affirm vs Klarna for furniture” is that you compare the specific offers you are shown on that specific order, side by side, using the total cost as the deciding number.
If only one of the two appears at checkout, you are not really choosing between brands. You are deciding whether that one offer, with its term, rate, and rules, is acceptable for the piece you want. And if the retailer does not offer either provider, the comparison becomes a guide to reading whatever plans that store does offer.
How Affirm and Klarna Work for Furniture Purchases
Both providers follow the same basic flow at a participating retailer: you choose your furniture, select the provider at checkout, answer a short application, and see the plan options you qualify for before you confirm. What you are offered depends on the purchase amount, the merchant, and your eligibility.
How Affirm works
Affirm offers two broad kinds of plans. Its Pay in 4 option splits a purchase into four interest-free payments, and Affirm states that Pay in 4 is 0% APR. Its longer pay-over-time plans are monthly installments; as of October 2026, Affirm’s disclosures state that the rate on these plans ranges from 0% to 36% APR based on credit and is subject to an eligibility check. Affirm also notes that options depend on the purchase amount, may vary by merchant, and that a down payment may be required. For furniture shoppers, the practical takeaway is that the plan shown to you will display the number of payments, the amount of each, and whether interest applies before you accept.
How Klarna works
Klarna’s Pay in 4 splits a purchase into four interest-free payments, with the first portion paid at purchase. Klarna’s U.S. disclosure language notes that a higher initial payment may be required for some consumers. For larger purchases, Klarna offers monthly financing, which it states is issued by WebBank. Klarna’s U.S. user terms state that applying for its interest-free payment plan, or for a closed-end loan from its banking partners, will not create a hard inquiry on your credit report or affect your credit score. As with Affirm, the plan you see at checkout is the one that counts, and its terms can differ from what you read in general guides.
In short, both providers pair a short interest-free plan with longer financing. For a furniture order, the question is which structure fits the size of the purchase and your budget, and which total you are comfortable paying.
Affirm vs Klarna vs Afterpay: Side-by-Side Comparison
The table below summarizes general features as stated on each provider’s official U.S. pages as of October 2026. It is a starting point, not a quote. Terms vary, are set by the provider, and depend on your eligibility, the merchant, and the purchase amount, so check each provider’s current terms before you apply.
| Feature | Affirm | Klarna | Afterpay |
|---|---|---|---|
| Short-term plan | Pay in 4, stated as 0% APR | Pay in 4, four interest-free payments | Pay in 4, interest-free installments generally over six weeks |
| First payment | A down payment may be required | Portion paid at purchase; a higher initial payment may be required for some consumers | First payment made upfront |
| Longer financing | Monthly pay-over-time plans; 0–36% APR based on credit | Monthly financing issued by WebBank | References a pay-monthly loan agreement; a finance fee may apply to certain transactions |
| Credit / eligibility | Subject to an eligibility check | Applying does not create a hard inquiry, per Klarna’s U.S. user terms | Must be 18 or older, a U.S. resident, and meet additional eligibility criteria |
| Late payments | Check the terms shown with your plan | Check the terms shown with your plan | No late fees when you pay on time (Pay in 4); late fees may apply |
| Offered at Mobilia Cleopatra | Yes | Not listed on our financing page | Not listed on our financing page |
Read the table as a map of plan types rather than a ranking. A short interest-free plan can cost less on a smaller order you can comfortably pay off in a few weeks. A longer plan may make a large order manageable month to month, but the total can be higher if interest applies. The right choice depends on the amount, the term, and your budget, not on which logo appears first.
Afterpay for Furniture: What a Pay-in-4 Plan Can and Cannot Do
Many shoppers search for Afterpay furniture stores because a pay-in-4 plan feels simple: a first payment upfront, then the rest over a few weeks. Afterpay describes its Pay in 4 as interest-free installments generally over six weeks at participating brands. To qualify, Afterpay states you must be 18 or older, a U.S. resident, and meet additional eligibility criteria. It also states there are no late fees when you pay on time for Pay in 4, that late fees may apply, and that a finance fee may apply to certain transactions.
Where Afterpay fits best is a smaller furniture purchase you can comfortably pay off within that short window, such as a side table, a lamp, or an accent piece. For a large carved sofa or a full living room set, a six-week schedule can mean installments that are too large for the weeks involved. A short plan can be easier to finish, but it can also be the wrong tool for a big order. In that case, a longer installment plan or a promotional financing account may be the more realistic option, as long as you have compared the total.
It is also worth being clear about availability. Afterpay is not one of the financing partners listed on our payment options page, so if Afterpay specifically is important to you, check the checkout page of whichever store you are considering. If what you want is the structure of a short plan, compare it with the shortest promotional terms the store does offer.
Which Payment Options Mobilia Cleopatra Offers
We want to be direct here, because a comparison article should not imply options that are not available. According to our financing page, Mobilia Cleopatra works with five financing partners. Klarna and Afterpay are not among them.
- Synchrony: a financing account for furniture purchases, with promotional plans such as up to 0% interest for up to 6 months for eligible buyers.
- Affirm: pay-over-time plans with a clear payment schedule shown before you confirm.
- Koalafi, Acima, and Snap Finance: lease-to-own options that may suit shoppers with limited or no credit history.
Our financing page notes that plans typically run for 3, 6, or 12 months, and that the exact length depends on the provider, your purchase, and your approval. Final terms, approval, and any fees are always set by the provider. Lease-to-own is a different kind of agreement from an installment loan, so read how ownership, fees, and early buyout work before you accept one. If credit history is your main concern, our guide to furniture with no credit check explains how those plans differ.
So if you arrived here comparing Affirm and Klarna, the practical path at our store is to compare Affirm against Synchrony’s promotional terms, or against a lease-to-own option if that suits your situation. If you would like a broader explanation of how these plans work, read our guide on what buy now, pay later furniture is. For help choosing a piece or confirming payment and delivery options, contact our team or call (909) 999-1442.
Using Affirm or Another Plan for a Sofa Set
Sofas and complete living room sets are among the pieces customers most often finance, and they are also where a payment plan can hide a poor decision. An Affirm sofa set is still a sofa decision before it is a payment decision. A monthly plan does not fix a frame that will not be named, or a sofa that does not fit the wall.
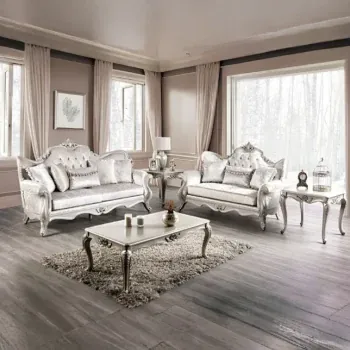
Start with measurements. Write down the wall length and the seat depth you want before you open any offer. A shallow seat reads as formal and upright; a deep seat reads as a lounge. A financed sofa that blocks a doorway or overwhelms the room is still the wrong sofa, and you will keep paying for it after it arrives. Then look at construction: the frame should be a named hardwood, the springs should be something the seller can describe, and the cushions should be replaceable. Our guide on how to choose luxury furniture walks through those checks.
Next, consider whether the size has to change. If a stock length does not fit your space, read about custom sofa sets before you finance a piece that almost works. Do not attach a plan to a custom order until the wood, the fabric, and the dimensions are written on the quote; a plan on an unfinished order is a plan on a guess. For the handmade Kleopatra Kingdom® pieces and the frame checks that apply to them, see handmade living room furniture.
Financing also does not change joinery, upholstery, or delivery. Ask who places the sofa in the room, because a carved frame should not be left at the curb. When the measurements and the build are settled, browse our sofa collection or complete living room sets, and read our guide to buy now, pay later sofa sets for more on financing seating specifically.
How to Choose the Right Plan for Your Furniture Order
Once the piece is right, the plan decision becomes much simpler. Work through these points with the actual offers in front of you.
- Compare the total, not the monthly figure. A longer term can cost more even when each payment looks smaller. If two offers appear on the same order, choose the lower total for a term you can realistically pay.
- Read what “0%” covers. A 0% offer is only 0% for the term printed on that offer and only if you meet its conditions. Check what happens when a promotional period ends.
- Know which product you are accepting. A pay-in-4 plan, a monthly installment loan, a financing account, and a lease-to-own agreement are four different products. If the label on the screen is unclear, do not confirm it.
- Check the late-payment rules. Each provider handles missed payments differently. Read the terms shown with your plan rather than relying on a general summary.
- Match the schedule to your budget. A short plan on a large order means large installments within a few weeks. Make sure the payments fit the weeks ahead.
- Ask about returns before you confirm. What happens if a financed piece is returned depends on the store’s policy and the plan you accepted.
Above all, do not pick a plan because the monthly figure is low if the frame, the fabric, or the size is wrong. Measure the piece, confirm the build, and only then compare totals. If the furniture is wrong, neither plan is the right one.
Frequently Asked Questions
How does Affirm or Klarna work for furniture purchases?
At a participating retailer, you choose your furniture, select Affirm or Klarna at checkout, and complete a short application. You then see the plans you qualify for, such as a pay-in-4 plan or longer monthly financing, with the payment amounts and any interest shown before you confirm. Options depend on the purchase amount, the merchant, and your eligibility.
Is Affirm or Klarna better for furniture?
Neither is better as a rule. The better plan is the one with the lower total cost for a term you can comfortably pay, with rules you have read. On a larger order, compare the full cost of each offer you are shown rather than the monthly figure or the brand name. If only one provider is available at the store you are buying from, the real question is whether that single offer is acceptable.
Is Affirm good for financing furniture?
It can be, if the plan you are offered fits your budget. Affirm offers both an interest-free Pay in 4 option and longer monthly plans that may carry interest based on credit. Read the total, the number of payments, and the rate before you accept, and make sure the furniture itself is right first.
Does Mobilia Cleopatra accept Affirm?
Yes. Affirm is one of the five financing partners listed on our buy now, pay later page, alongside Synchrony and the lease-to-own options Koalafi, Acima, and Snap Finance. Approval and terms are set by the provider.
Can I use Klarna or Afterpay at Mobilia Cleopatra?
Klarna and Afterpay are not among the financing partners listed on our buy now, pay later page. If you want a short interest-free plan or longer financing, compare the options we do offer, or call (909) 999-1442 to ask our team about current payment options.
Can I use Afterpay at furniture stores?
Some furniture retailers accept Afterpay, but availability varies by store, so check each retailer’s checkout page. Afterpay’s Pay in 4 is generally spread over about six weeks, which tends to suit smaller furniture purchases better than a large set.
Are buy now, pay later plans worth it for furniture purchases?
They can be useful when the plan’s total cost is clear, the payments fit your budget, and the furniture is the right size and build. They are a poor choice when a low monthly figure hides a higher total, or when the piece itself does not suit your room. Measure first, confirm the build, and treat the plan as the last step of the purchase.
Final Thoughts
Affirm and Klarna offer similar plan structures for furniture: a short interest-free option and longer financing that may carry interest. Afterpay adds another pay-in-4 choice that tends to suit smaller orders. The deciding factor is never the brand. It is the total cost over the term, the rules you agree to, and whether the piece you are financing is the right one for your room.
At Mobilia Cleopatra, you can compare Affirm with Synchrony’s promotional financing and our lease-to-own partners. Choose your furniture first, measure the space, and then review the payment options on our financing page before you apply. Terms vary, are set by each provider, and can change, so always check the provider’s current terms before you confirm a plan.
This article is general information, not financial advice.