Free shipping · 0% for 6 months · White-glove available

Buy Now, Pay Later Sofa Sets: How to Finance a Couch or Living Room Set

Reviewed by the Mobilia Cleopatra design team
Quick answer: Yes, you can buy a couch or a complete sofa set with buy now, pay later. At Mobilia Cleopatra you choose your sofa, sectional or living room set, then pick a financing partner at checkout: Synchrony, Affirm, or the lease-to-own options Koalafi, Acima and Snap Finance. Plans typically run 3, 6 or 12 months, and the provider sets the final terms, approval and any fees. Before you apply, measure the room, confirm how the sofa is built, and compare the total cost of the plan rather than just the monthly payment.
A sofa set is one of the largest purchases most households make for the living room, and it is also one of the pieces people live with longest. That is why so many shoppers look for a buy now, pay later sofa option: it lets you bring home the right seating now and spread the cost over a schedule you can plan around.
Financing, though, only solves the payment. It does not make a sectional fit a narrow wall, turn a vague frame description into solid hardwood, or lower the total you will pay over the term. The best results come from making the furniture decision first and the payment decision second, then reading the plan in front of you line by line.
This guide walks through how buy now, pay later works for couches and living room furniture, which options are available on our buy now, pay later furniture page, how interest-free, deferred-interest and lease-to-own plans differ, and how to choose a sofa, a full set, or a single accent chair that is worth paying for over time.
How Buy Now, Pay Later Works for a Couch or Sofa Set
Buy now, pay later (BNPL) lets you take delivery of furniture while dividing the price into scheduled payments. Instead of paying for a sofa set in one lump sum, you agree to a plan with a provider and repay it over weeks or months. The retailer is paid by the provider; your agreement is with the provider.
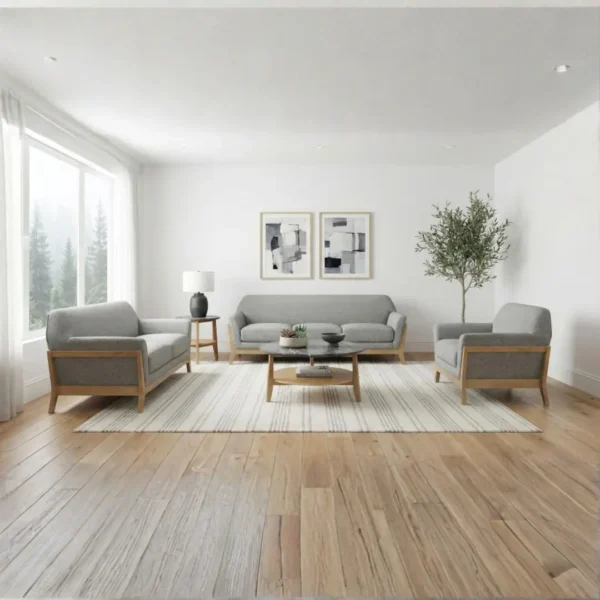
How BNPL Furniture Financing Works
The three plan types you will see
- Short pay-in-four plans. The price is split into four payments, usually with the first one due at checkout. The Consumer Financial Protection Bureau describes the classic BNPL loan this way. These work best for smaller orders.
- Monthly installment plans. A longer schedule with fixed monthly payments. Depending on the provider and your eligibility, the plan may carry no interest or an APR.
- Lease-to-own. You lease the furniture and own it after completing the lease or exercising an early purchase option. Lease-to-own usually costs more than the retail price in total, so it is worth comparing carefully.
What happens at checkout
You add your sofa or set to the cart, select a partner, and complete a short application. The provider decides on approval and shows the payment schedule. According to the CFPB, you can generally qualify for a BNPL loan without a hard credit inquiry, but each provider has its own process, so check what the application screen tells you before you submit. For the full background on how these programs work, see our guide to what buy now, pay later furniture is.
Which Payment Options Mobilia Cleopatra Offers for Sofas
Sofas and complete living room sets are the pieces our customers finance most often. As of October 2026, our payment page lists five partners:
- Synchrony – a financing account for furniture purchases, with promotional plans such as up to 0% interest for up to 6 months for eligible buyers.
- Affirm – pay-over-time plans with the payment schedule shown before you confirm. On its own site, Affirm says Pay in 4 is 0% APR and longer plans range from 0% to 36% APR based on credit, subject to an eligibility check.
- Koalafi, Acima and Snap Finance – lease-to-own options that may suit shoppers with limited or no credit history.
Plans typically run for 3, 6 or 12 months; the exact length depends on the provider, your purchase and your approval. If you want a side-by-side look at how different BNPL providers structure their plans, we cover that in our Affirm vs Klarna comparison, so we will not repeat it here. Note that Mobilia Cleopatra does not offer Klarna or Afterpay; the five partners above are the full list.
If you are researching BNPL solutions for furniture stores more broadly, this mix is a useful model of what shoppers look for: a financing account with promotional periods, an installment lender with a clear schedule, and lease-to-own partners for people still building credit. Having all three means most buyers can find a plan that fits.
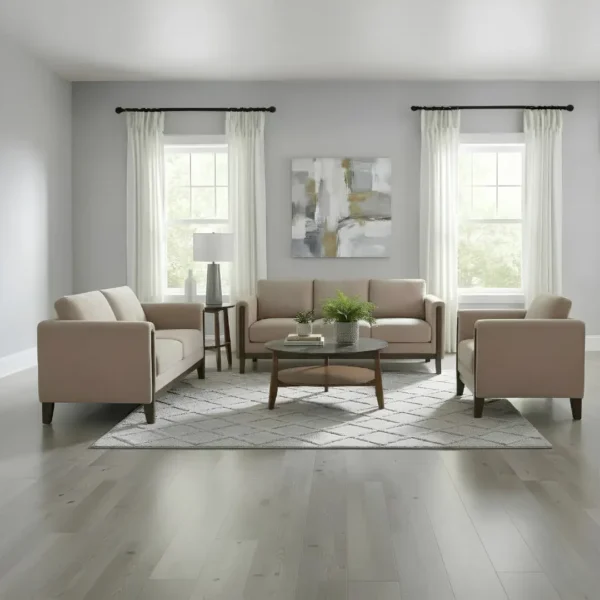
Buy Now Sofa Sets
Interest-Free, Deferred-Interest and Installment Plans
The words on a financing offer matter more than the monthly figure. Three terms come up again and again with sofa financing.
True 0% plans
A true zero-interest plan does not charge interest during the term. You pay back the purchase price in the scheduled payments, provided you follow the plan’s conditions. Searches like “0 interest sofa” usually mean this kind of offer, and it is the simplest to budget for.
Deferred-interest promotions
Some promotional financing works differently. The CFPB explains that an offer worded “no interest if paid in full” within a set period is a deferred-interest promotion: interest is tracked from the purchase date, and if the full balance is not paid by the end of the period, that interest can be added to what you owe. If your plan uses this structure, set your own payment so the balance is cleared before the promotion ends.
Installment plans with an APR
A fixed-APR installment plan gives predictable monthly payments, but the total you repay is higher than the sofa’s price because of interest. Compare the total repayment amount on the screen, not only the monthly payment, especially if a longer term makes each payment look small.
Also remember that the CFPB notes most BNPL companies charge late fees for missed payments, and unpaid debt can hurt your credit. Before you accept, read the late-payment terms and whether you can pay early without a penalty.
Choosing the Right Sofa Before You Finance
A payment plan cannot fix a sofa that is the wrong shape for the room. Start with a tape measure: the wall or floor area the sofa will occupy, the walkway around it, and every doorway, hallway and stair turn on the delivery path. Ask for overall width, depth and height, plus seat height and seat depth, before you choose a plan.
Sectional sofas
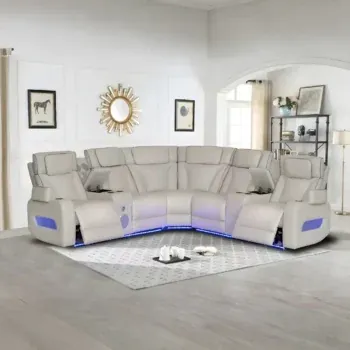
Large sectional sofas maximize seating and help define an open-plan living area. Check which side the chaise or corner falls on, and confirm that each section can be carried through your entry on its own.
Classic sofas and loveseats
A traditional three-seat sofa suits formal living rooms and pairs easily with a loveseat or accent chairs. Browse our sofa collection for traditional, French-style and Victorian silhouettes.
Modular seating
Modular systems can be rearranged as your household or room layout changes, which makes them a flexible long-term choice for families.
Custom sofas
If no stock size fits, a custom order lets you specify dimensions, upholstery and configuration. Get the custom quote and confirm the details first, then choose the financing; the plan should follow the order, not the other way around. Our guide to custom sofa sets explains how that process works. The genuinely handmade pieces we sell are the Kleopatra Kingdom® collection and explicit custom commissions; the rest of our catalog is a curated range of name-brand furniture.
What Makes a Sofa Worth Paying For Over Time
If you are going to make payments on a sofa for months, it should still be comfortable and sturdy long after the last payment. Much of what determines that is hidden under the upholstery, so ask questions before you commit.
Frame and joinery
Look for a frame described as a named hardwood, ideally kiln-dried to reduce moisture and movement. Ask how the joints are made: mortise-and-tenon joints, dowels and reinforced corner blocks are signs of careful construction, while a frame that is never named is a reason to keep asking.
Suspension and cushions
Comfort depends on the support system. Eight-way hand-tied springs and sinuous springs are both used in quality seating; ask which one a sofa uses. Cushions that combine high-density foam with a fiber or feather wrap tend to balance support and softness, and removable cushion covers make long-term care easier.
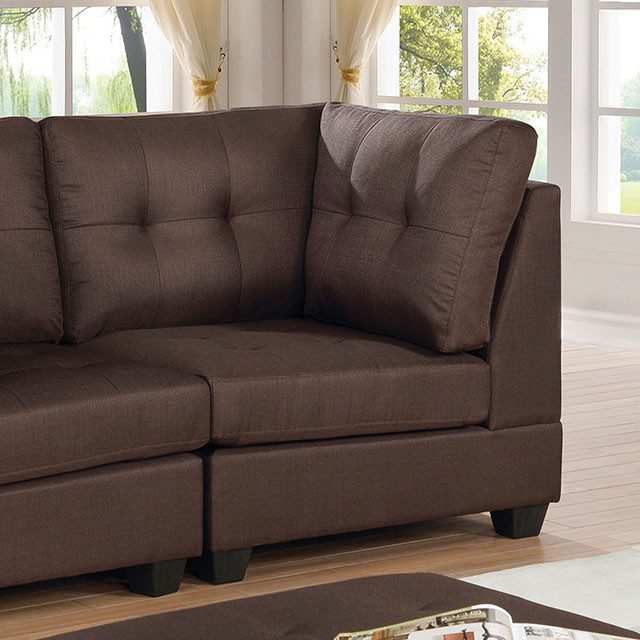
Choosing Materials That Increase Long-Term Value
Upholstery that suits your household
Top-grain and full-grain leather age with character. Performance fabrics resist everyday stains, which matters with children or pets. Velvet adds depth and a formal look, though cotton velvet shows crushing more than performance velvet. Linen gives a relaxed feel in transitional rooms. Choose the material for how the room is used, not only for how it looks in a photo.
Style that will last
Because financing stretches the purchase over time, a timeless style is a safer choice than a passing trend. Traditional, French-style and Victorian designs, with their balanced proportions and carved detailing, tend to stay relevant in a formal living room for many years.
Financing a Complete Living Room Set
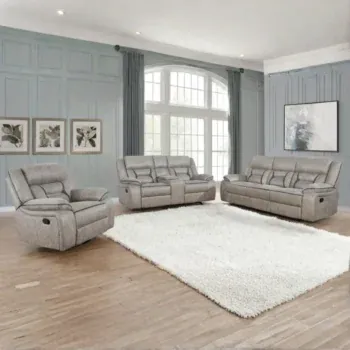
One advantage of financing is that you can furnish a room in one go instead of adding pieces over several years. A coordinated living room set gives you matching sofa, loveseat and chair finishes from day one, and you can add coffee tables, side tables or an ottoman to the same order.
If you are wondering how to afford a complete living room set in installments, a simple approach helps:
- Set a total budget first. Decide what the whole room should cost, including delivery, before you look at monthly figures.
- Prioritize the seating. The sofa and main chairs get the most use; tables and accessories can be added later if the budget is tight.
- Choose a term you can finish. A 3-, 6- or 12-month plan should leave room in your monthly budget for other expenses.
- Read the total repayment amount. Compare it with paying in full, and with the other partners available at checkout.
- Avoid stacking plans. The CFPB warns that taking out several BNPL loans in a short time can make payments hard to track. One plan for the whole room is easier to manage than several small ones.
Delivery planning also matters for a full set. Confirm the delivery date, who brings the pieces inside, and whether assembly is included, so the order arrives in the right room and the right condition.
Financing Accent Chairs and Single Seating Pieces
Not every financed purchase is a full set. Many customers use the same payment partners for a single statement piece: one or a pair of accent chairs, a loveseat, a recliner or a chaise. The same rules apply, just on a smaller scale.
- Measure first. Note the open floor space, the door swing and the walkway. An accent chair’s seat should sit close to the sofa’s seat height, not tower over it, and a tall carved back can crowd a room with a low ceiling.
- Match the plan to the order size. A short pay-in-four plan can make sense for a single chair, while a longer installment plan is usually better suited to a full set. Ask what is available for your order amount.
- Check the build. The frame should be a named hardwood or metal, and the upholstery should have a named fiber. On a traditional chair, ask whether the carved legs are part of the wood or applied separately.
- Finance a pair only if both fit. One chair that suits the room is better than two that block the walkway.
If you are buying a chair to match a sofa, measure the sofa first so the two sit at the right height and scale together.
Questions to Ask Before You Apply
Before you accept any financing offer for a sofa or living room set, it helps to have clear answers to these questions:
- Is this a true 0% plan, a deferred-interest promotion, an installment plan with an APR, or a lease?
- What is the total repayment amount over the full term?
- Does the application involve a credit check, and what kind?
- What happens if a payment is late, and are there fees?
- Can I pay the balance early without a penalty?
- Is a down payment required?
- Are custom orders eligible for financing, and when does the plan start?
- What is the delivery timeline, and what warranty covers the furniture?
- How do returns work for a financed item?
If you have limited credit history, read our guide to furniture with no credit check before you choose between an installment plan and lease-to-own. For help with a specific order, call our team at (909) 999-1442. You can also see seating in person at our Upland showroom at 280 N Benson Ave, Suite 6, Upland, CA 91786.
Frequently Asked Questions
Can I buy a couch with buy now, pay later?
Yes. Add the couch to your cart, choose a financing partner at checkout and complete the application. At Mobilia Cleopatra the options are Synchrony, Affirm, and the lease-to-own partners Koalafi, Acima and Snap Finance. The provider decides on approval and sets the terms.
Can I finance a full living room furniture set?
Yes. You can finance a complete living room set, including the sofa, loveseat, chairs and tables, in a single order. Set a total budget first, then choose a plan length you can comfortably finish.
Can I get a sofa with buy now, pay later if I have bad credit?
It depends on the provider. Lease-to-own partners such as Koalafi, Acima and Snap Finance may approve shoppers with limited or no credit history, but approval is always decided by the provider, and lease-to-own usually costs more than the retail price in total.
Is there 0 interest sofa financing?
Some plans have promotional periods with no interest for eligible buyers. As of October 2026, our payment page describes Synchrony promotional plans of up to 0% interest for up to 6 months, and Affirm says its Pay in 4 is 0% APR. Check whether an offer is a true 0% plan or a deferred-interest promotion.
Do buy now, pay later sofa plans require a credit check?
Each provider has its own process. The CFPB notes that you can generally qualify for a BNPL loan without a hard credit inquiry, and Affirm describes an eligibility check for its plans. The application screen will tell you what applies.
Can I finance a single accent chair?
Yes. Our payment partners can be used for furniture across the store, including accent chairs, loveseats and recliners. Measure the space and confirm the chair’s frame and fabric first, then compare the plans offered for your order amount.
Is it better to finance a sectional or pay upfront?
Paying in full avoids any interest or lease costs. Financing can make sense when the payments fit your budget and the plan’s total cost is clear. Compare the total repayment amount with the cash price before you decide.
Final Thoughts
Buy now, pay later can be a practical way to bring home a well-built sofa set, a sectional or a single accent chair without waiting to pay the full amount at once. It works best when the furniture decision comes first: measure the room and the delivery path, confirm the frame, suspension and upholstery, and choose a style you will still enjoy years from now.
Then treat the plan as its own decision. Know whether it is a true 0% offer, a deferred-interest promotion, an installment plan with an APR, or a lease, and compare the total repayment amount, not just the monthly payment. Choose a term you can finish comfortably, and keep to one plan per room where you can.
When you are ready, explore our sofas and living room sets, and review every partner and current offer on our financing options page.
This article is general information, not financial advice. Terms, approval and fees are set by each financing provider and can change; always review the offer shown to you before you accept.